
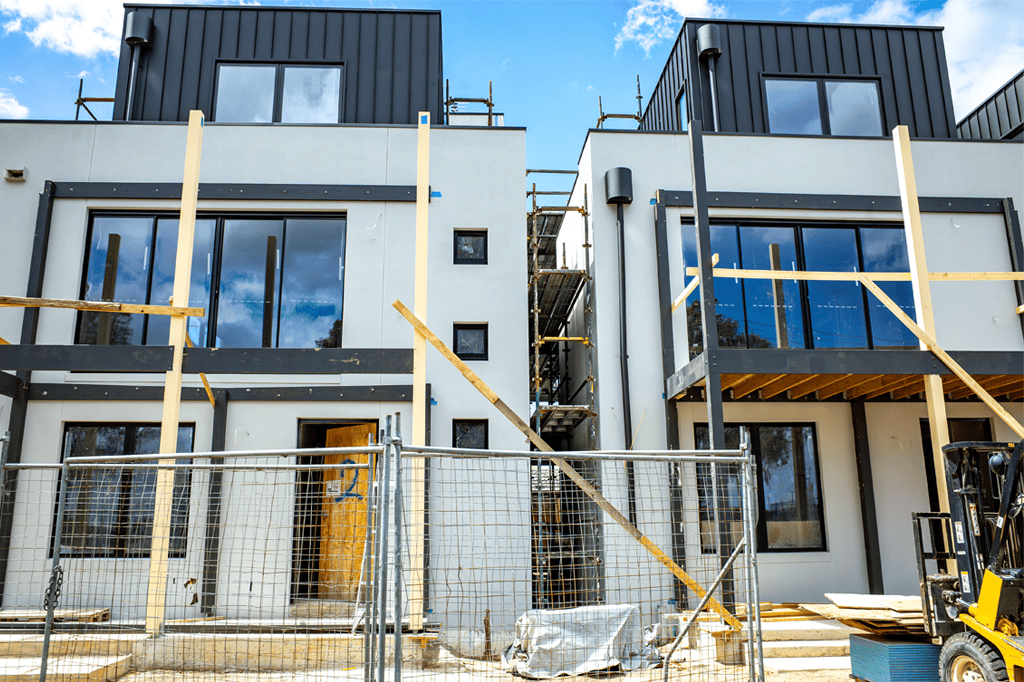
In August 2026, Sydney developer Bathla Group entered voluntary administration owing more than $3.6 billion, leaving thousands of partially built homes in limbo.1 Since the collapse, several private credit funds have capped or paused investor redemptions to protect their own liquidity. ASIC Chair Sarah Court has called the conditions the sector’s “first real test.”2
This story isn’t simply about one developer. It’s a story about funding certainty, and the risks that private lenders carry when compared to non-bank, warehouse-backed lenders like Prime Capital.
Not every non-bank lender is a private lender
Non-bank lenders now fund more than 40 per cent of residential construction lending in Australia, up from around 17 per cent in December 2019 — a shift the Reserve Bank attributes largely to the growth of private credit, itself a form of non-bank lending.3 But while private lenders are often categorised under the non-bank umbrella, understanding the distinction between them is crucial.
Non-bank lenders are typically institutional and regulated, structured much like a bank. Private lenders range from high-net-worth individuals to boutique funds, operating with less oversight.5 George Obeid, President of the MFAA National Equipment and Commercial Finance Forum, notes that while private credit is significant in supporting Australian businesses and property, “not all [private] lenders operate to the same standards.”5 That inconsistency has invited increased ASIC scrutiny, and it’s why brokers need to remain particularly discerning.
The second distinction is about funding. ASIC’s own definition of private credit separates non-bank lenders “that rely primarily on warehouse financing from banks or corporate institutions” from those funded by retail or wholesale investor capital.4 One draws on a secured facility from an institutional balance sheet. The other draws on a pool of investor money that can be recalled.
Not every private lender needs an Australian Credit Licence to operate, and structuring a facility as business credit can remove it from the National Consumer Credit Protection Act’s reach entirely.5 Non-bank lenders operate under a more consistent regulatory framework, regardless of how the loan is structured.
Approved isn’t the same as funded
Many private credit vehicles are structured as open-ended funds, letting investors withdraw periodically, usually every month. The catch: that capital is locked into multi-year construction and development loans, not cash sitting in reserve. If redemption requests start outstripping new money coming in, the fund has one real lever: limit what investors can withdraw, to protect everyone still in the fund.2
This isn’t a sign of bad lending. It’s structural: a loan book funded by capital that can be recalled will always face this constraint. It creates a gap between an approved loan and a funded one, a gap that’s largely administrative in a warehouse-backed model.
The distinction is worth checking at application stage: is the facility a committed line from an institutional balance sheet, or an open-ended fund drawing on investor capital that can be recalled? That answer predicts how a loan behaves under market stress.
Where Prime Capital fits
Prime Capital is a non-bank business lender, not a private lender. Our loans are backed by committed warehouse facilities funded by major banks, structured across senior, mezzanine and junior tranches. Those facilities are contracted and available on drawdown, regardless of investor sentiment elsewhere in the market.
This matters most to our brokers’ developer clients, where funding certainty makes all the difference. Our Business Construction loan was built to support property development businesses funding new residential construction projects. With approvals within 24 hours and BDMs and credit working hand in hand, you can help keep projects moving with confidence. The same funding structure backs every product in our range.
Talk to our team about a scenario, or submit through Prime Approve. https://www.primecapital.com/approve/?
Sources
- Catie McLeod, “Embattled Sydney property developer Bathla warns it could fold by the end of the week,” The Guardian, August 2026 (theguardian.com)
- “Private Credit Funds Have Restricted Redemptions Since Before Bathla’s Collapse, and Construction Lending Tightened With Them,” The Good Builder, August 2026 (thegoodbuilder.com.au)
- Reserve Bank of Australia, “Recent changes in credit markets and their implications for monetary policy,” RBA Bulletin, February 2026 (rba.gov.au)
- EY-Parthenon, Annual Australian Private Debt Market Overview, March 2026 (ey.com)
- MFAA, “Navigating the rise of private lending: opportunities and risks for brokers,” 30 May 2025 (mfaa.com.au)